Britain won't run out of gas this Winter. It will pay for it.
Posted on 23 September 2026
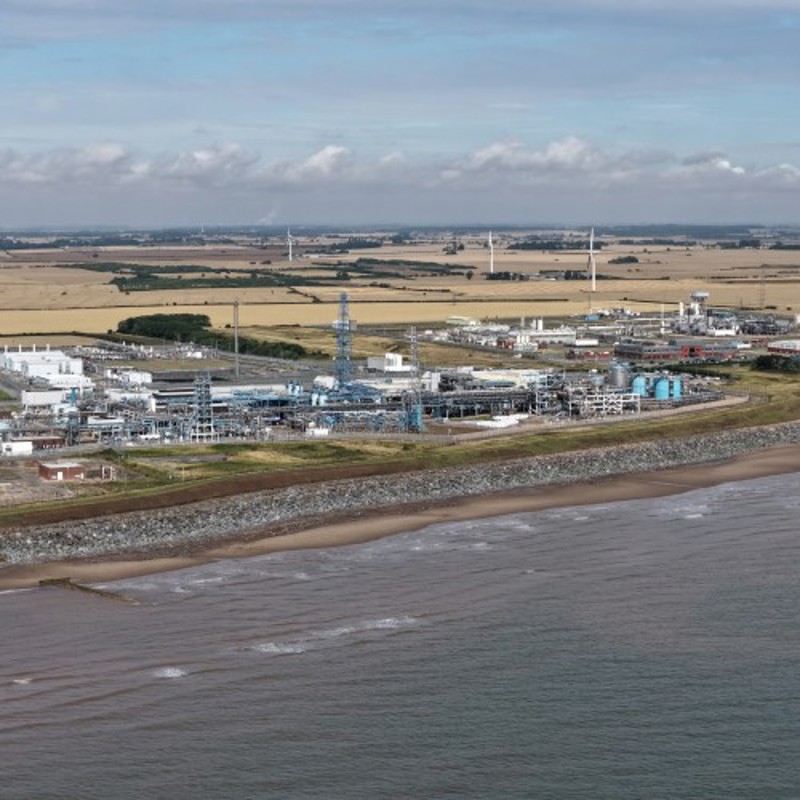
Britain’s largest gas store is empty. Centrica says Rough will stay that way through the Winter and close by spring unless it is brought into a regulatory support model, and its Chief Executive has warned that the UK has almost no gas in storage for the coming winter. Against the backdrop of the Hormuz crisis, headlines about shortages followed quickly but are often conflating two different risks. One is a physical shortfall, meaning not enough molecules to meet demand. The other is price. Our view is that the first is unlikely and the second has already happened.
The storage picture, honestly stated
The numbers are not pretty. British storage sits around 51% full, with Rough and Humbly Grove both empty, and European storage was only 68.66% full on 15 September. That leaves Europe entering winter with among the lowest inventories in two decades, well short of the EU’s 80% target. Britain’s position is structural and long-standing: at the time Rough reopened in 2022, the UK held roughly nine days of storage, against 89 in Germany, 103 in France and 123 in the Netherlands.
Storage was never how Britain got through winter
Storage is a small part of the GB winter supply stack. In winter 2024/25 storage withdrawals supplied 3.5 bcm of a 45.4 bcm total, against 15.4 bcm from the UKCS, 16.1 bcm from Norway and 9.8 bcm of LNG (Chart 1). That is under 8% of supply. National Gas notes that current GB storage is predominantly fast-cycling medium-range capacity, shaped by decades of indigenous production, whereas continental Europe relies on seasonal long-range storage. Our salt caverns are built for peak days and cold snaps, and they fill and empty several times a winter. They do not carry the season.
On peak days the picture is similar. National Gas put 2025/26 supply capability at 565 mcm/d against a 1-in-20 peak demand of 482 mcm/d (Chart 2). The storage figure within that was already reduced on the assumption that Rough would deliver nothing significant, and LNG terminal capacity has risen to 175 mcm/d after the South Hook and Isle of Grain expansions. The system was planned around an empty Rough a year ago. The 2026/27 outlook is due shortly, and we expect tighter margins but the same conclusion.